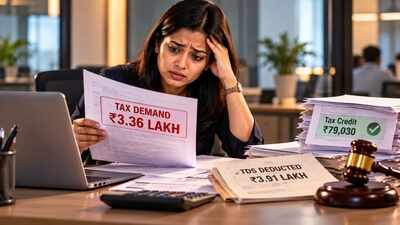
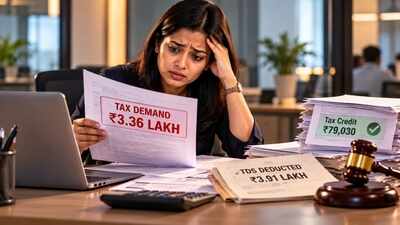
Your employer cuts Tax Deducted At source or TDS from your salary, but doesn’t deposit it. You get a tax demand notice. What do you do?A Mumbai-based IT professional faced this very situation when she received a tax demand of Rs 3.36 lakh, even though she had claimed Rs 3.91 lakh as TDS credit in her income tax return (ITR).
What the case is about
For Assessment Year 2019-20, the woman reported an income of Rs 18.41 lakh in her ITR and claimed credit for Rs 3.91 lakh in TDS. However, she was given credit for only Rs 79,030, resulting in a tax demand of Rs 3.36 lakh.The reason was that her employer, an IT services company, had deducted TDS from her salary but had not deposited the amount with the government.She approached the Centralised Processing Centre (CPC) for rectification on several occasions, but her efforts did not resolve the issue.She subsequently filed a first appeal, which was rejected on the ground that it was time-barred. She then challenged the matter before the income tax appellate tribunal (ITAT), where she eventually got relief.
Why ITAT Mumbai ruled in taxpayer’s favour
The ITAT Mumbai observed that the woman had not received credit for the entire TDS amount because her employer had deducted tax from her salary but failed to remit it to the revenue.As the deducted amount was not deposited, the complete TDS credit did not appear in her Form 26AS. This led to the denial of her Rs 3.91 lakh TDS claim.She, however, produced several documents to establish that the tax had actually been deducted from her salary by her employer. These included her salary slips, Form 16, bank statements and other supporting records.After considering the documents and referring to recent rulings of the Supreme Court and a High Court, the tribunal held that an employee cannot be made liable for a tax demand where the employer has deducted tax at source from the employee’s salary income but failed to deposit the deducted amount with the government.The Rs 3.36 lakh tax demand will therefore also be nullified once the Assessing Officer verifies her claim of Rs 3.91 lakh in TDS and grants her the full credit, according to an ET report.In this case, the taxpayer succeeded because she was able to establish that TDS had actually been deducted from her salary.A taxpayer who can demonstrate that TDS was deducted, using documents such as Form 16 and salary slips, can rely on Section 205 of the Income Tax Act, 1961. In such a case, the Department cannot seek to recover the same tax from the employee.Once the TDS credit is allowed, the Rs 3.36 lakh tax demand will effectively stand nullified.Raghav Bajaj, Partner, Khaitan & Co says that the ITAT Mumbai ruling reinforces an important safeguard: where salary tax has demonstrably been withheld by an employer, the taxpayer employee should not bear the consequences of the employer’s failure to remit it.Section 205 of the Income-tax Act, 1961 (corresponding to section 401 of Income-tax Act, 2025) draws a bright line: once tax is deducted, the obligation to remit it falls on the deductor, not the deductee.“By directing verification and grant of credit, the Tribunal recognises the evidentiary value of Form 16, salary records and banking trails. For taxpayers and practitioners, the implications are both reassuring and instructive,” he tells TOI.On the dispute resolution front, this decision makes clear that automated CPC processing under Section 143(1) – which matches TDS claims against Form 26AS – cannot be the final word where genuine deductions have occurred.“A mismatch in Form 26AS, standing alone, does not extinguish a legitimate TDS credit,” he says.According to Kuldip Kumar, Partner at Mainstay Tax Advisors LLP, the decision of the Mumbai ITAT is a useful reiteration of an important principle relating to TDS credit.There have been several other judgments of different Benches of the ITAT and various High Courts that have favoured the assessee in this regard.“The legal position is now strongly supported by a consistent line of judicial decisions that, where tax has actually been deducted at source but has not been deposited by the deductor, the assessee should not be denied the corresponding TDS credit or be made liable to pay the same tax again, provided the assessee is able to establish that the tax was in fact deducted,” Kumar tells TOI.Importantly, Kumar notes that this principle is not confined to tax deducted from salary. It can also apply to TDS deducted from other domestic payments, including contractor or professional fees, rent, interest, dividend and similar payments.
Lessons for employees
In relation to their financial affairs, it is important for taxpayers to maintain proper documentation to establish that TDS was actually deducted.According to Kumar, for salaried taxpayers, this could include salary slips, employment letters and bank statements evidencing receipt of the net salary. In the case of other payments, copies of invoices, contracts or agreements, payment advice, ledger accounts and bank statements showing receipt of the net amount could serve as supporting evidence.It is also advisable to review Form 26AS/AIS periodically and reconcile the TDS reflected therein with the TDS actually deducted. Where a deduction is not reflected, the taxpayer should, where possible, promptly write to the employer or payer and request confirmation and correction. Such contemporaneous correspondence can also become important corroborative evidence if the deductor subsequently fails to deposit the TDS or file the relevant TDS statement.“Given the increasing reliance on electronic processing, a TDS mismatch may result in an automated demand being raised when the TDS claimed in the return is not reflected in Form 26AS/AIS. In such circumstances, the taxpayer should promptly seek rectification with the CPC / jurisdictional Assessing Officer with appropriate documentary evidence and seek grant of the TDS credit and consequential rectification of the demand,” Kuldip Kumar says.